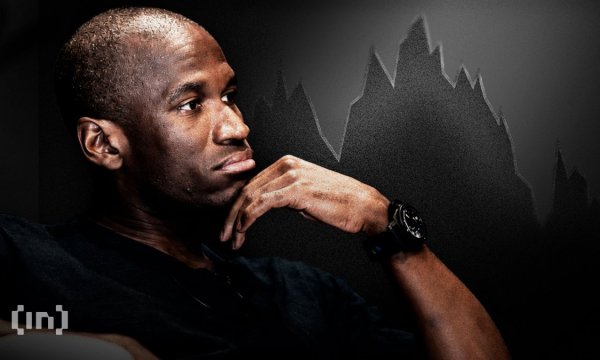
Arthur Hayes Says US Insurers Are Insolvent Over AI Debt: What if He's Right?
Arthur Hayes says the US insurance industry is already insolvent once AI-linked debt is marked to market. The claim rests on captive reinsurance structures that book worthless promises as real capital.
Forensic accountant Thomas Gober, publishing through analyst Nick Nemeth, found $1.54 trillion in affiliated reinsurance against $657 billion of surplus. Strip that reinsurance out, and 29 of the top 30 US insurers are technically insolvent.
Three Vermont captives Gober examined held just 3.7% of the assets needed to cover their combined promises.
What Happens if He’s Right?
Nothing changes as long as the underlying contracts go untested. The trigger, Hayes argues in his newsletter, would be a wave of downgrades on AI data center debt.
Insurers already hold a growing share of the AI data center debt market. That ties their solvency to whether AI labs keep buying compute.
Private credit funds have already gated investor withdrawals once this year. That warning sign runs through the same private credit debt strain now facing insurers.
State guaranty funds are meant to backstop failed insurers, but payouts cap around $250,000 to $300,000 per policy. Those funds are financed by surviving insurers, many of which lean on the same reinsurance model.
Retirees holding annuities from these insurers could see real losses if the backing reinsurance is as thin as described.
To Put it Simply…
This is a chain of dominoes, and the question is what happens if the first one falls.
Insurers have used accounting tricks to make their reserves look stronger than they really are. If AI companies slow down buying computing power, the loans behind those data centers get downgraded, and insurers holding that debt suddenly need more real money than they actually have.
That’s when the trick gets exposed. Some private lending funds are already showing similar stress, a warning sign for what could be coming.
If an insurer fails, the safety net is thin: government-backed funds only cover $250,000 to $300,000 per policy, and that safety net is funded by other insurers who may be just as exposed.
So ordinary people with retirement annuities could be the ones left holding the loss.
This may sound familiar as it is exactly what happened in the 2008 housing collapse, which the movie, The Big Short, was based on.
In fact, Steve Eisman, one of the real investors profiled in The Big Short, was on a podcast to discuss this exact research and called it “a slow brewing scandal which could one day be a great financial crisis.”
What Would be the Outcome for Bitcoin?
This leaves two outcomes. Regulators let insurers fail and absorb the backlash, or the government intervenes to stop it.
Hayes has made this same argument before. He linked the Fed’s defense of the yen to fresh dollar liquidity. He also compared Bessent’s Treasury buybacks to Yellen’s 2023 playbook.
The logic repeats here. Whether the government bails out insurers or buys AI compute directly, both paths expand the money supply. Hayes treats that expansion as bullish for Bitcoin (BTC).
Whether Hayes is right depends on disclosures regulators have kept confidential for years. If the hole is even a fraction of what forensic accountants describe, the fallout would reach far beyond crypto markets.
Source: BeInCrypto
Cryptocurrency News
Random quote about money
"Деньги - очень полезная штука. Они позволяют не делать того, чего ты не любишь делать, а я не люблю делать почти ничего."
Interesting posts in other sections of the blog
 ↑
* to search the proxy database, just enter a country name, e.g. Russia, USA, Thailand